
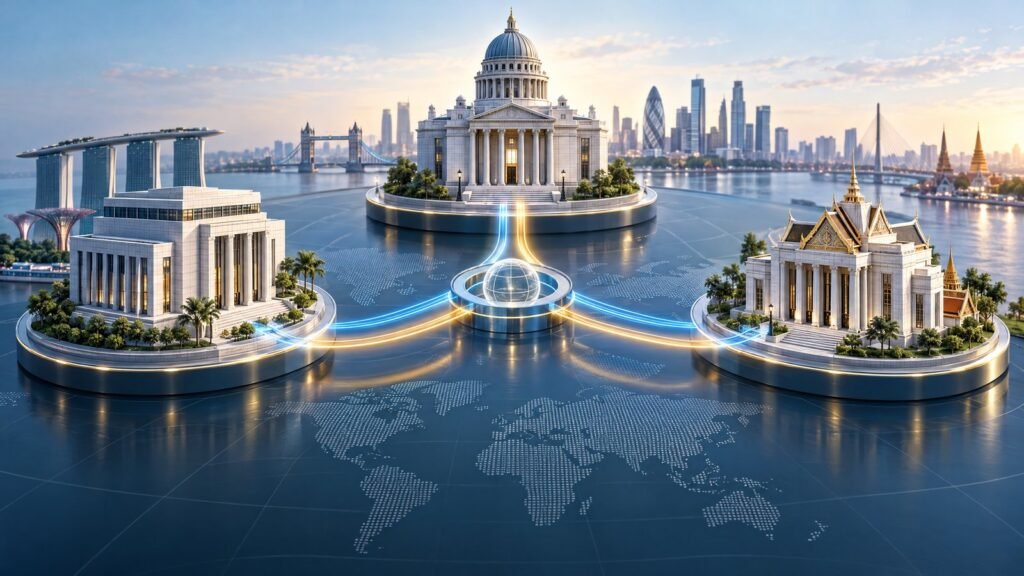
Three central banks have demonstrated a way to coordinate foreign-exchange settlement across different payment technologies without moving everyone onto one shared system. Project Meridian FX APAC connected simulated environments from the Bank of England, the Monetary Authority of Singapore and the Bank of Thailand. It was a research trial—not a live stablecoin network or a new retail payment service.
What did Project Meridian FX APAC test?
The central banks published their joint findings on November 13. The experiment linked conventional real-time gross settlement systems and systems using distributed ledger technology. Partior developed and integrated the prototype coordination service, called the Synchronisation Operator.
The important feature was the link between separate transfers. Rather than replacing each central bank’s infrastructure, the operator coordinated the conditions under which payments could proceed across those systems. The results suggest that different technical designs need not prevent interoperability, although differences in system capabilities made implementation more complicated.
How does payment-versus-payment reduce risk?
Payment-versus-payment, or PvP, makes delivery of one currency conditional on delivery of the other. This addresses the risk that one party pays away its currency but does not receive the currency it bought. The prototype tested coordinating both sides so the linked settlement could complete together or not proceed.
A second use case combined multiple foreign-exchange obligations through multilateral netting. Offsetting eligible payments can reduce the liquidity banks need to settle them. The trial demonstrated the technical approach, not a fixed percentage saving that every future participant can expect.
Why does this matter for stablecoin payments?
Stablecoins and modernized bank infrastructure are different approaches to cross-border payment problems. Meridian’s experiment used central bank money in test environments; it did not launch a dollar-pegged token. Its relevance to crypto is the question of whether new forms of digital money and existing settlement rails can work across system boundaries rather than forming isolated networks.
That is a different design from the PNC pilot that converts USDC payments into dollars. The separately reported Project Faro stablecoin funding plan also concerns a different initiative. Neither should be confused with a production launch of Meridian FX APAC.
What has not been proven yet?
The primary executive summary says the work did not reproduce the full foreign-exchange trade lifecycle, live participants or production operating conditions. Selected failure tests were encouraging, but prolonged outages and non-overlapping operating hours were among the real-world constraints not fully tested. The findings therefore do not establish round-the-clock commercial readiness.
There is also a legal boundary. Technical atomicity—making linked payment legs complete together—is not automatically the same as legally recognized settlement finality across jurisdictions. A live service would still need clear rules on responsibilities, oversight, governance and the legal effect of each transfer.
Is Meridian FX APAC live, and what comes next?
The published work is an experiment, not an announced commercial service. The Bank of England says it plans a live synchronization interface in 2028, but that plan should not be read as a guaranteed launch date for this three-country trial. Further work could broaden participation, currencies and transaction scenarios while addressing legal and operating arrangements.
For digital-asset users, the takeaway is narrower than a new payment token: the trial provides evidence that existing and ledger-based wholesale systems can coordinate settlement. Whether that becomes a usable service depends on the practical and legal work still ahead.