
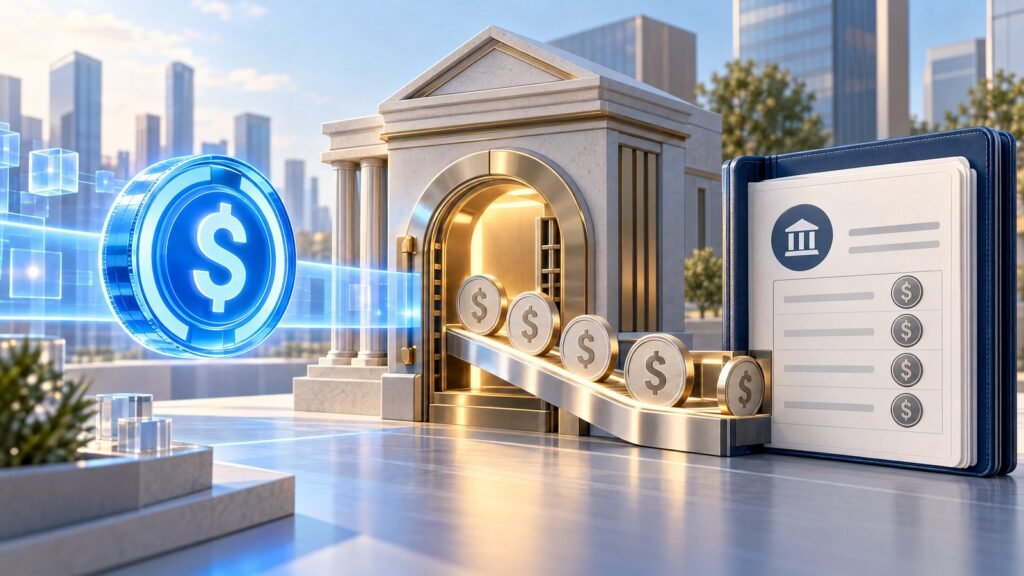
PNC’s stablecoin payments pilot gives eligible corporate and institutional clients a way to receive USDC without keeping the incoming payment in crypto. The bank and Coinbase announced on November 9 that the tokens will be converted automatically into U.S. dollars and deposited into a designated PNC account.
The limited pilot connects a blockchain payment to a familiar bank balance. It is not a retail crypto service or a launch for every PNC customer. Its significance is narrower: testing how stablecoin receivables can fit into a company’s existing treasury workflow.
How do PNC stablecoin payments work?
According to PNC’s announcement, the incoming asset is USDC on Ethereum. Coinbase’s payment infrastructure handles the digital-asset side, while PNC provides the banking and treasury relationship. USDC is converted at a one-to-one rate into dollars for the receiving client’s designated account.
That distinction matters for the recipient. A business can accept a stablecoin-funded payment through the pilot, but the announced destination is a dollar deposit—not a requirement that its treasury team hold or trade USDC. PNC is not announcing a new stablecoin of its own.
Coinbase’s matching announcement identifies its Payment APIs as the infrastructure behind the arrangement. Neither announcement turns that technical integration into a promise that every transfer will settle instantly under every condition.
Who can use the USDC payments pilot?
The stated audience is eligible PNC Corporate & Institutional Banking clients, on a limited pilot basis. The announcements do not say that ordinary personal checking-account customers can activate it, or that all businesses already banking with PNC automatically qualify.
Reuters’ November 9 report describes PNC as testing and learning with clients. That framing is more useful than treating the announcement as evidence that stablecoins have already become a standard corporate-payment rail.
Why does automatic dollar conversion matter?
Much of the practical question around business crypto payments is what happens after the token arrives. Automatic conversion is meant to connect the blockchain leg with a bank-based cash-management process, rather than leave the recipient to arrange a separate sale or transfer.
PNC points to faster access to funds and cross-border-payment efficiency as potential benefits it is testing. Those are the bank’s objectives, not independently measured results from this pilot. The releases do not publish transaction volumes or a comparison of end-to-end costs.
This is also different from Uber’s HSBC tokenized-deposit treasury test. A stablecoin payment converted into a bank deposit and a tokenized bank deposit are different structures, even when both aim to improve how companies move money.
What remains unconfirmed?
The announcements do not provide pilot client numbers, a fee schedule, a complete list of payment corridors or a timetable for broader availability. Businesses would still need the actual eligibility and operating terms before judging whether the service fits their receivables.
The pilot should not be confused with the separate OCC stablecoin-rule implementation timeline. A bank testing a payment service is not, by itself, evidence that every regulatory requirement has changed or that a general rollout has been approved.